Taxi driver insurance
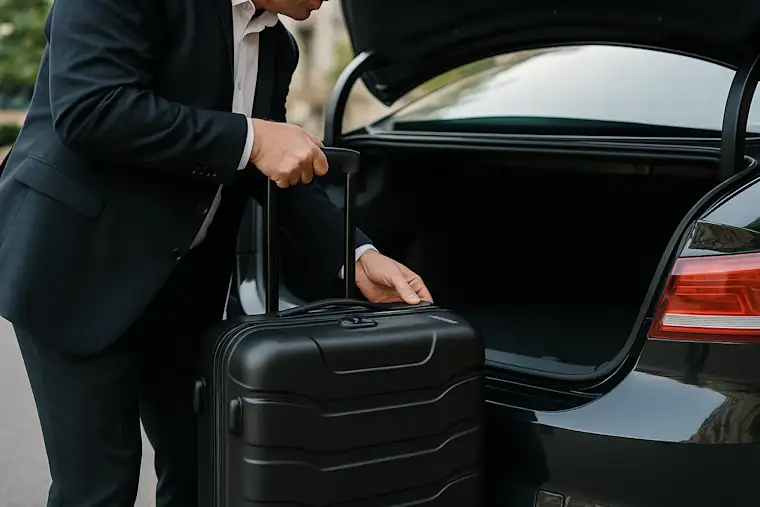
A passenger hurt getting out of the car, or a bag damaged in your boot. Your motor policy doesn't cover either, and both can result in a claim against you.
Public Liability from €7.55 per month, with cover up to €6.5 million per claim


Business insurance, done differently.

Fully online business insurance in Ireland.

A few questions and you're covered.

No lock-in, no long contracts.

Excess from €0, up to €6.5 million of cover.
Why take out business insurance as a taxi driver?
You're in and out of the car all day, helping with bags on wet kerbs and in the dark. Public liability covers you if a passenger is hurt or their property is damaged, and it's the cover hotels, corporate accounts and airport work ask you to show.
Your motor policy stops at the kerb. Compulsory motor insurance covers the vehicle and the driving. It doesn't cover a passenger hurt on the footpath while you help them with a bag, or a case you damage loading it into the boot.
Clients ask to see it. Public liability isn't required by law in Ireland. But airport and hotel contracts, corporate accounts and public tenders routinely ask you to show cover before they'll give you the work.
The claim lands on you, not your motor insurer. A fractured wrist on a footpath is a personal injury claim against your business. The legal costs start the day the letter arrives.
What is Public Liability insurance?
Public liability covers you when your work injures someone else or damages something that belongs to them. For a taxi driver that means the part of the job that happens outside the vehicle, and the passengers and property you are responsible for while they are with you.
How it works: if someone claims you caused injury or damage, Insify handles the claim and pays what is owed, up to your cover limit. Your excess is the part you pay yourself on each claim.
What it covers: injury to a passenger or a member of the public, damage to property belonging to someone else, and the legal costs of defending the claim.
Cover that fits your work: choose €1.25 million, €2.5 million or €6.5 million per claim. Council permits commonly ask for at least €2.6 million and public tenders often specify €6.5 million, so check what your contracts require before you pick.
Is it required?: Public liability isn't required by law in Ireland. However, many hotels, corporate clients, airport operators and school transport contractors require proof of cover before they'll give you work. Cover starts from €7.55 per month.
Who needs it: taxi drivers working ranks, airport runs, school or hospital contracts, and anyone carrying passengers' luggage, wheelchairs or equipment.

What does our insurance cover for taxi drivers?
Your public liability cover follows the work, not just the vehicle. It answers for injury and damage you cause to other people while you are doing your job.
Passengers and the public: injury to a passenger getting in or out, or to a pedestrian at the kerb, is a third-party injury claim and sits here rather than with your motor insurer.
Property in your care: luggage, wheelchairs, instruments and shopping are covered as standard while they are in your care, up to €5,000 per claim and €10,000 per year.
Damage to property at a pick-up or drop-off: a hotel door you catch with a case, or a glass panel you knock with a bag.
Staff, if you have them: employers' liability can be added for €13 million per claim if you take on a second driver. It isn't compulsory in Ireland.
What sits elsewhere: anything arising from driving the vehicle belongs to your compulsory motor policy. This cover sits alongside it and does not replace it.

Some examples, for illustration
A passenger slips at the kerb while you help them out with their luggage and fractures a wrist.
A suitcase is crushed as you load it into the boot and the laptop inside is broken.
You catch a hotel's glass door with a luggage trolley while dropping a fare at the entrance.
A passenger slips at the kerb while you help them out with their luggage and fractures a wrist.
A suitcase is crushed as you load it into the boot and the laptop inside is broken.
You catch a hotel's glass door with a luggage trolley while dropping a fare at the entrance.
Examples are for illustrative purposes only. Compensation depends on the exact circumstances of the claim. No rights can be derived from these examples.
Your business insurance with Insify SmartGuide
Taking out insurance can be quick. Making sure you have the right cover is another matter. With Insify SmartGuide, you don't sign a contract blindly. You ask all your questions, and get clear, immediate and personalised answers, before you take out a policy.
Are you covered if you accidentally damage a client's equipment while working?
What excess should you choose?
Are you protected in the event of a dispute with a client?
Insify SmartGuide guides you step by step to understand what's covered, what isn't, and why. In just a few clicks, you build insurance that's truly tailored to your business, with complete confidence. Try Insify SmartGuide. Understand your insurance before you need it.

How to choose the right insurance as a taxi driver?
Criteria to compare:
The cover offered: check the policy follows the whole job, not just time behind the wheel. Airport runs, rank work, school and hospital contracts, wheelchair-accessible work and handling passengers' luggage should all be declared and all be covered.
The price: compare premiums across insurers, but an attractive price can hide exclusions that matter in passenger transport. Read what is carved out before you compare the monthly figure.
The excess: know what stays at your own expense when a claim happens, and check whether it changes by claim type. It is the number people notice only after an incident.
The exclusions: watch for undeclared work, licence and permit conditions, transport outside the categories you declared, and anything the policy treats as belonging to a motor policy instead.
The service: in passenger transport an incident can happen at any hour. Choose an insurer that is reachable and that knows the sector. At Insify, our online support team knows the specifics of your work.
Mistakes to avoid: do not take a generic policy that ignores what passenger transport actually involves, and do not assume your motor cover answers for everything that happens on a job. To secure your business today, discover our Public Liability insurance.
More than 40,000 entrepreneurs trust us
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
The cover itself was sorted quickly, and when I later needed support I got that fast too.
Our answers to your questions about taxi public liability insurance
No, and this is the most important thing to understand before you buy. Your vehicle, and everything that happens as a consequence of driving it, is covered by the compulsory motor insurance you already hold. Public liability sits alongside that policy and answers for injury or damage you cause to other people in the course of your work but outside the act of driving. The classic examples are a passenger injured while getting in or out, a bag damaged while you load it, and a building you catch while dropping someone off.
Public liability isn't required by law in Ireland. However, many hotels, corporate clients, airport operators and school transport contractors require proof of cover before they'll give you work. Cover starts from €7.55 per month.
Cover starts at €7.55 per month including taxes. Your price depends on your turnover, the limit and excess you pick, and whether you add employers' liability for staff. A driver working alone on street and rank work sits at the lower end. Someone on airport contracts with a second driver and a €6.5 million limit pays more. Run a quote to see yours. It takes 2 minutes, with no commitment.
This is exactly the situation public liability is for, provided the injury does not arise from the driving itself. If a passenger trips on the kerb as you hold the door, or is hurt while you help them into the seat, that is a third-party injury claim against you and this cover responds. It pays what you are found liable for up to your cover limit, and it pays the legal costs of defending the claim, which are often the larger figure early on. If the injury happens because of how the vehicle was driven, it belongs to your motor policy instead.
Property belonging to other people while it is in your care is covered as standard on this policy, up to €5,000 per claim and €10,000 in a year. That covers the ordinary things that go wrong in this job: a case crushed in the boot, a laptop bag dropped, an instrument or a wheelchair damaged in handling. Note the limit is per claim, so an expensive single item can exceed it.
Yes. The cover follows your work rather than a fixed address, so it applies at the airport, on a rank, at a hotel entrance, at a client's premises and on the street. What matters is that the work you are doing is work you declared when you took out the policy.
The excess is the part of every claim you pay yourself before Insify pays the rest. If your excess is €500 and a claim settles at €3,250, you pay €500 and Insify pays €2,750. For turnover up to €500,000 you can choose €0, €250, €500, €1,000 or €2,500, and €500 is the default. A higher excess lowers your monthly premium but costs you more on the day something happens, so choose the figure you could actually pay at short notice rather than the one that makes the quote look best.
Yes. There is no long-term commitment and you can cancel anytime. You can also change your cover limit, adjust your excess or add employers' liability as your business changes, without starting a new policy. If you take on a second driver, add a contract that requires a higher limit, or stop doing a type of work, update the policy at that point. Keeping it current is what makes sure a claim is paid, and it takes a few minutes online.